
A bipartisan credit card bill being pushed in Congress would deliver a financial windfall to the nation’s largest retailers while leaving consumers and community lenders to pick up the tab, the head of a national credit union trade group warned this week.
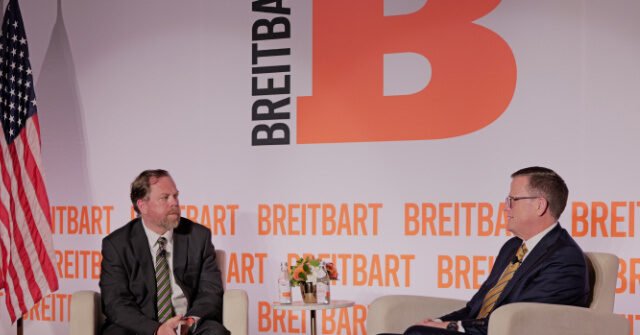
Scott Simpson, president and CEO of America’s Credit Unions, joined Breitbart News economic editor John Carney on stage Tuesday in Washington, D.C., to argue against the Credit Card Competition Act, which he characterized as a “transfer of wealth to the retail oligarchs in this country.”
The legislation, originally introduced in 2022 by Sens. Dick Durbin (D-IL) and Roger Marshall (R-KS) with support from both parties, was reintroduced in January. Its stated aim is to introduce more competition into the credit card market and challenge what supporters call the Visa-Mastercard duopoly.
Under the bill, banks holding more than $100 billion in assets would be required to give merchants a choice of at least two networks to process a credit transaction, at least one of which could not be Visa or Mastercard. Currently, stores that accept credit cards are effectively locked into whichever payment network the card runs on and pay whatever fee that network sets. Visa and Mastercard together handle more than 80 percent of the market.
Taking Aim at the Durbin Precedent
Durbin’s name is already attached to a similar effort in the debit card space. The so-called Durbin amendment was added late in the drafting of the 2010 Dodd-Frank financial reform law and directed the Federal Reserve to cap the fees retailers pay for debit card processing. Simpson called that provision an “eleventh hour legislative stunt” and argued it never delivered on its promises.
“There is no evidence that any of that savings have pushed to the consumer,” he said, contending that merchants kept the difference rather than passing it along at the register.
He predicted the same dynamic would play out if the CCCA became law: cheaper processing options would fatten retailers’ margins instead of lowering prices for shoppers.
Who Pays the Price
Simpson framed the fight as one pitting large corporate chains against the members his organization represents — a constituency he described as broadly middle class.
“Credit unions represent soldiers, sailors, teachers, [and] first responders,” he said. “That’s who’s going to be harmed.”
The trade group leader went further, suggesting the legislation could force credit unions to reconsider the products they offer altogether. “We are going to be left with no other choice than to retreat, pull [our] product away from the kitchen tables of this country to continue to support big box retailers,” Simpson said.
Fraud and Cybersecurity Concerns
Beyond the pricing question, Simpson raised alarms about what the shift could mean for fraud protection and data security. Carney noted that many stakeholders are worried the change could affect how card issuers, and especially credit unions, are able to combat fraud.
Simpson said the interchange fee system exists precisely to fund that protection. “That’s what the interchange system is built for — is to establish contracts with the American consumers and reliable protection,” he said. “Well, that protection comes at the expense of the issuer.”
He pointed to a pattern in major data breaches, arguing that retailers lack the built-in incentives that card issuers have to safeguard consumer information. “We look at the biggest data breaches in the history of our country and they tend to come from retailers because they don’t have incentives,” Simpson said. “They’re not incentivized by the system to protect that data, and so it gives us zero confidence as issuers.”
The CCCA’s supporters have long argued that the current fee structure amounts to a hidden tax on merchants that gets baked into consumer prices anyway. The bill’s backers say opening processing to additional networks would introduce price pressure and innovation into a market dominated by two players.
Whether the measure can advance in the current Congress remains an open question, but the debate over interchange fees has now stretched across three presidential administrations — from the 2010 debit card caps through the current push on credit, and the same core argument, that consumers ultimately win or lose depending on how the rules are written, sits at the center of it.
Source: www.breitbart.com — https://www.breitbart.com/economy/2026/09/09/exclusive-americas-credit-unions-president-scott-simpson-says-credit-card-competition-act-would-benefit-retailers-over-consumers/